Introduction: From general-purpose software to the industry’s operating system
In horizontal markets such as CRM, ERP and HR software, dozens of products compete for the same customer. As the differences between products narrow, competition usually collapses into price. The spread of AI agents is adding further pressure on general-purpose software priced per user (seat).
In vertical software, the point is not just to sell a piece of software. The goal is to sit at the centre of a specific industry’s workflow and to manage the money, goods and data that move along it.
The scale of this shift is visible in public companies too. Toast, the restaurant software company, generated roughly $5 billion in revenue from financial services last year, while subscription revenue stayed at $936 million. In other words, the payments business is more than five times the size of the software business. In the second quarter of 2026, vertical software accounted for more than half of deal volume in the software sector.
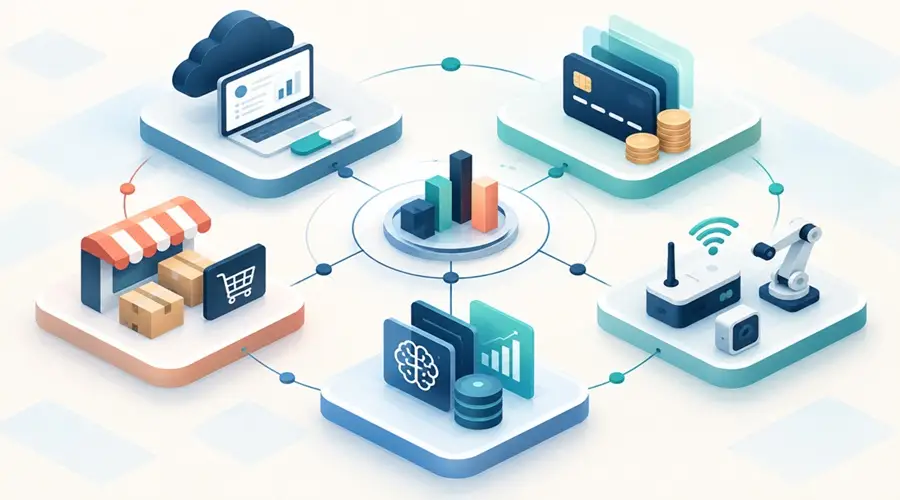
Türkiye has a strong foundation for this shift. Decades of manufacturing and trading experience in sectors such as textiles, automotive supply, logistics, construction, agriculture and food have produced software teams that learned the business on the ground. Most of these companies still sell licences or subscriptions today. Yet their customers’ payments, supply chains and data already flow through the software they use.
Foreign investors are no longer buying a software licence; they are buying a share of an industry’s flow of money, goods and data.
Beyond SaaS: Multiple revenue models in vertical software
Subscription is a good starting point for vertical software, but it does not have to be the only source of revenue. As the platform becomes central to an industry’s day-to-day operations, new opportunities open up in payments, procurement and data. These revenue streams can be added step by step, in line with customer needs and partnerships, rather than all at once.
1. Embedded finance
Financial products such as payments, factoring, micro-loans and insurance can be offered from inside the software. According to Andreessen Horowitz’s analysis, adding financial products to vertical software can increase average revenue per user (ARPU) by 2–5x. More than 40% of customers adopt embedded finance products, and each new product grows revenue by around 40% on average.
An important advantage of this model is the data the platform already holds. Orders, invoices and collection history can help identify financing needs. In Türkiye, for example, this could mean factoring for textile suppliers based on e-invoice data, pre-harvest input financing for farmers, or bundled fuel and insurance solutions for logistics companies. Such products are usually launched in partnership with a licensed bank, factoring company or payment institution.
2. Transaction-based revenue and the B2B marketplace
A software platform can bring an industry’s buyers and sellers together and earn a commission per transaction. In B2B marketplaces, the commission rate (take rate) typically ranges from 3% to 15%, depending on the category and the additional services offered.
Fragmented supply chains such as yarn and fabric, spare parts, construction materials or scrap metal can be a good fit for this model. The platform can make trading easier while building on the industry’s existing relationships and ways of working.
3. Data and AI as a service (DaaS)
Once properly anonymised, the industry data accumulated on a platform can be turned into services such as price indices, demand forecasts or credit scoring models. These solutions can be offered to banks, insurers, manufacturers or public institutions.
However, the legal framework for this revenue model has to be considered from the outset. Customer contracts must permit the use of data, and anonymisation and explicit consent processes must comply with KVKK (Türkiye’s data protection law) and GDPR.
4. Hybrid models integrated with hardware
IoT sensors, machine connectivity, remote monitoring and maintenance licences can tie the software into the physical infrastructure of a factory or business. This integration can also make it harder for the customer to switch to another solution.
Even so, it is important to assess the economics of hardware separately from software revenue. Investors tend to treat companies with gross margins above 70–75% as software companies. Companies below that level may be valued more like services businesses, at 2–4x revenue or EBITDA multiples. Pricing hardware separately and reporting recurring software revenue on its own therefore makes the business model easier to understand.
| Revenue model | Revenue source | Strength in investors’ eyes | Watch-out |
|---|---|---|---|
| Subscription (SaaS) | Per-user, per-module, per-location fees | Predictability, high margin | Growth capped by the number of user licences |
| Embedded finance | Margin on payments, factoring, lending, insurance | 2–5x ARPU uplift, low churn | Licensing, credit risk, compliance cost |
| B2B marketplace | Commission on transaction volume | Network effects, large TAM | Liquidity is hard to build; cohort evidence required |
| Data and AI (DaaS) | Reports, indices, scoring models | High margin, proprietary data asset | KVKK/GDPR, data rights |
| Hardware-integrated | Sensor, maintenance, connectivity licences | Maximum switching cost | Gross margin and inventory risk |
The key financial metrics foreign investors look at
For foreign VC and PE funds, the first question is not “how fast are you growing?” but “how durable is your growth?” A multi-revenue model strengthens the answer on four metrics.
NRR – Net Revenue Retention
NRR shows how much revenue the same group of customers generates for the company one year later. Upsells to those customers are added, while revenue from customers who leave or downgrade is deducted.
A rate above 100% means the company is growing through its existing customers even without winning new ones. Investors pay close attention to this: companies with NRR above 120% find buyers at valuations 2–3 times higher than those below 100%.
A multi-revenue model lifts NRR mechanically. Subscription revenue is capped by seat count, whereas payment and transaction revenue grows with the customer’s business volume. At Toast, a restaurant that stays on the platform for five years ends up spending 6 times its starting annual amount, and most of that expansion comes from financial services, not software.
Low churn: Barriers to exit
For a customer that runs its payments, financing and supply chain through a single platform, switching systems does not just mean moving to new software; it means rebuilding the company’s entire operation from scratch. In the Turkish market, statutory integrations such as e-Invoice (e-Fatura), e-Waybill (e-İrsaliye) and social security (SGK) reporting make this bond even stronger.
In a healthy business, annual gross revenue retention (GRR) is expected to stay above 90%. Customer concentration also deserves attention: a single customer accounting for more than 10% of total revenue is a serious red flag, particularly for venture capital and private equity (PE) funds.
Rule of 40
Annual growth rate + EBITDA margin ≥ 40%: the rule sums up the balance between growth and profitability in a single number. Companies with a Rule of 40 score above 50 and NRR above 120% change hands at 7–9x ARR in private transactions. In a multi-revenue model, this needs to be read alongside the blended gross margin: high-volume but low-margin payment revenue can inflate the score while eroding the margin.
A note on Türkiye: In a high-inflation environment, a growth rate in Turkish lira is meaningless to an investor. Always report the Rule of 40, NRR and revenue growth in USD or EUR.
The TAM, SAM, SOM paradox
First, let’s look at what these terms mean:
TAM (Total Addressable Market): The theoretically largest market your product or service could reach. It assumes you can reach your entire target audience, without accounting for limits such as geography, language or budget.
SAM (Serviceable Available Market): The size of the market you can serve today with your business model and current geographic reach. Limits such as language, operations and product scope are taken into account. SAM is the reachable portion of TAM.
SOM (Serviceable Obtainable Market): The market share you can realistically capture in the short to medium term once you factor in competition on the ground, your sales capacity and your operational limits. It shows your actual target within SAM.
“Mid-sized dye houses in Türkiye” is, on its own, a narrow market for a fund. But those dye houses’ annual spending on yarn, dyes, energy, financing and insurance is an enormous pool. The right TAM calculation is based not on the software budget but on the volume that could flow through the platform:
- Subscription TAM: Number of target companies × average annual subscription fee
- Embedded finance TAM: Number of customers × adoption rate × annual payment volume per customer × net revenue share
- Marketplace TAM: The industry’s annual procurement volume (GMV) × commission rate
- Geographic expansion: The equivalent of the same vertical in MENA, the Balkans and Eastern Europe
Investors trust this bottom-up calculation and actual adoption rates rather than big top-down numbers.
Current software valuation multiples and the “multiple premium”
In 2026, software valuations settled at a new equilibrium after a sharp correction: the SaaS Capital index fell from 7.0x to around 3.8x ARR in 14 months. But the average is misleading; the gap between two companies of the same size has never been this wide, and that gap is largely determined by the revenue model.
| Company profile | Typical multiple |
|---|---|
| Lower mid-market SaaS in private markets, median | ~4.5x ARR |
| Vertical software overall (H1 2026) | ~5.5x revenue |
| Vertical B2B SaaS, $1–50M ARR | 4.0–8.0x ARR |
| Healthcare IT (regulatory barrier + embedded payments) | ~8.5x revenue |
| Vertical software with embedded finance / integrated payments | 6–14x ARR |
| AI-native, best in class | 10–18x |
| Services-heavy model with gross margin below 70–75% | 2–4x |
Subscription only, or multiple revenue streams?
Vertical software companies that sell only subscriptions mostly stay in the 4–8x ARR range. Platforms that run embedded finance and transaction volume can reach 6–14x. The premium comes from the fact that financial revenue survives even if a competitor enters the core software, and that it ties NRR to the customer’s growth.
Two important caveats:
- Net revenue is valued, not gross volume. Report your payment revenue on a net basis, after transaction costs. Presenting gross payment volume as revenue destroys credibility in the first week of due diligence.
- Marketplace revenue needs proof. Transaction-based revenue is not as predictable as contracted subscriptions. To pay the same multiple, investors want to see cohort data, repeat-purchase curves and a track record of match rates.
The AI premium: It doesn’t come with the label
Buyers sort software companies into three groups: exposed to AI (seat-based products doing work an agent could do), resilient to AI (regulated verticals, proprietary data, deep workflows) and AI-native. AI-native companies command a 40–80% premium over comparable traditional software. The advantage of vertical software is that it already has the proprietary industry data to carry that premium. But investors buy the measurable impact of AI on NRR, margins and efficiency, not the label.
European data: Software still commands a premium, but buyers are selective
| Region | Software development (EV/EBITDA) | Regional average, all sectors (EV/EBITDA) |
|---|---|---|
| DACH | 8.9x | 5.4x |
| UK&I | 8.0x | 5.4x |
| France | 7.9x | 5.3x |
| Nordics | 7.9x | 5.4x |
| Southern Europe | 7.7x | 5.4x |
| Netherlands | 7.4x | 5.0x |
| CEE (Central and Eastern Europe) | 7.0x | 5.3x |
According to Dealsuite‘s September 2026 survey of 815 advisory firms, software development is priced between 7.0x (CEE) and 8.9x (DACH) EBITDA in European SME transactions, against an all-sector average of 5.3x. CEE, the closest reference point for Türkiye, is the region with the lowest multiple in software.
Signal: The number of interested buyers per software development company fell from 11.8 to 10.7 in a year. In four of the seven regions, advisers expect fewer software deals because of uncertainty over AI’s impact on business models. Buyers are looking for the model that will benefit from AI, not the one that will be harmed by it.
These figures are EBITDA multiples at SME scale and also cover project-based software development; they should not be compared directly with ARR multiples. The same survey shows that in half of sale processes the seller’s expectation exceeds market value by an average of 25%, and that this gap causes 29% of processes to collapse.
Global opportunities and risks for companies in Türkiye
Opportunities
- R&D and cost advantage: Competitive engineering costs, technology development zones and R&D centre incentives make it possible to generate the same revenue at a higher margin than a competitor in Western Europe. This difference feeds directly into the Rule of 40 score.
- Digital infrastructure: Thanks to systems such as e-Invoice, e-Waybill and e-Archive, Turkish companies’ commercial data is more digital than in many other markets. This is ready-made raw material for embedded finance and data products.
- Regional leadership: A vertical platform that has matured in Türkiye offers a ready reference in markets with a similar industrial structure across Europe, MENA, the Balkans, Central Asia and Africa.
- Foreign-currency revenue: Every unit of revenue earned abroad offsets currency risk and partly decouples the valuation from the Türkiye risk premium.
Risks: The local market trap
Success in the Turkish market can turn into a trap without anyone noticing. As the product is shaped around local regulation, traditional sales cycles and lira pricing dynamics, it grows at home; but to a global investor looking in from outside, it becomes a structure that is hard to scale. The most common mistakes when expanding abroad:
-
Embedding local regulation in the core: If local statutory integrations such as tax, e-invoicing or social security are hard-coded into the core of the software, every new country means developing the software all over again. This layer needs to be separated from the centre of the product and built as modules that can be swapped easily.
-
Copying the financial model as it is: A factoring or payments structure set up with a local bank or financial institution in Türkiye will not be valid in another country. Each new market requires its own financial set-up, based on its own regulation and locally licensed partners.
-
Launching the marketplace without liquidity: A marketplace that goes live without sufficient transaction density and volume on both the buyer and the seller side quickly turns into an abandoned space.
-
Spreading across many countries at once: Going deep in a single target market and earning strong references is far more valuable than having a weak, scattered presence in several countries.
-
Converting the lira price straight into foreign currency: Instead of multiplying the price by the exchange rate and offering it abroad, it is essential to set a new pricing strategy based on the dynamics of the target market, local purchasing power and the value competitors offer.
The right approach is the discipline of Land and Expand: enter with one country, one sub-segment and a strong reference customer, then grow revenue per customer by adding new revenue layers.
A strategic roadmap for founders: How do you attract foreign investment?
1. Plan the move from a single revenue model to multiple revenue models
Trying to switch on all revenue layers at the same time can spread operations too thin. Investors want to see a balanced roadmap in which each stage feeds on the data built up in the previous one:
-
Foundation: First secure subscription revenue; track churn and net revenue retention (NRR) regularly by customer cohort.
-
Payments: Partner with a licensed payment institution and start collecting payments from inside the software. This is the fastest financial step to roll out and the one with the lowest risk.
-
Financing and insurance: Use the invoice and order flows accumulated in the system to refer customers to bank, factoring or insurance partners. Never carry credit and default risk on your own balance sheet.
-
Marketplace and data: Once you have reached sufficient transaction volume and customer numbers on the ground, add supply-chain intermediation and anonymised data products to the system.
2. Grow the share of foreign-currency revenue
As the share of foreign currency in total revenue rises, your hand gets stronger when the investor brings up the Türkiye risk premium. In practice, foreign-currency revenue above 30% starts to move the company from the category of “a software firm dependent on Türkiye” to “an international platform operating from Türkiye with a cost advantage”. In domestic contracts, pricing in or indexed to foreign currency, and payment volume denominated in foreign currency, also improve revenue quality.
3. Build the story: “We are not a software product, we are this industry’s infrastructure”
A good equity story tells the investor not how many licences you have sold, but how much of the industry flows through you:
- Show the volume: Annual payment volume (TPV) and procurement volume (GMV) flowing through the platform, together with your share of the industry total.
- Report revenue layers separately: Subscription, financial services, transaction and data revenue each on its own, with net revenue, gross margin and adoption rate for each.
- Position Türkiye as a tough-market test: Show that a model that grows amid high inflation, complex regulation and a price-sensitive customer base will also work in other emerging markets.
- Offer proof in a second country: A single reference customer abroad is more convincing than the best-prepared market analysis.
- Clean up the structure early: Document that the intellectual property belongs to the company, complete KVKK/GDPR compliance and financial partnership agreements, and, if needed, consider a foreign holding structure before the round.
- Set realistic valuation expectations: Earn-outs, deferred payments and rollover (reinvestment) structures are the tools most often used to bridge the expectation gap.
Next step
Before you start investor meetings, you can measure how ready your company is with our Investment Readiness Score and review the steps in our guide to the company sale process. To have the process managed from start to finish, you can draw on our sell-side advisory service.
Conclusion: From software company to industry infrastructure
The value of vertical software is no longer measured only by how many licences it sells. Investors look at how much of an industry’s flow of money, goods and data passes through the platform. While companies that sell only subscriptions stay in the 4–8x range, platforms that run this flow through embedded finance, marketplaces and proprietary data can talk about 10x and above. Turkish vertical software companies’ industrial and trading know-how, digitised commercial data and cost advantage are a strong starting point for this shift. Companies that turn this into a foreign-currency-based, reportable and multi-layered revenue model will sit at the foreign investor’s table not as a software vendor, but as an industry’s infrastructure.
Where does your revenue model place you in the valuation range?
At Anatrica Partners, we support vertical software companies with valuation, investment and sale readiness, capital raising and cross-border M&A processes.
Published: 6 October 2026 – Last updated: 6 October 2026
This article is for general information purposes only; it does not constitute investment, legal or tax advice.
Sources
- Dealsuite, European M&A Monitor, Edition 8 (September 2026) – dealsuite.com
- HiringThing, 2026 Vertical SaaS Trends: So Far
- Apideck, Embedded Finance for Vertical SaaS
- Rainforest, Embedded Payment Processing: A Guide for Vertical SaaS
- ClearlyPayments, How Much Revenue Can a Software Company Generate from Embedded Payments
- Multiples.vc, B2B Marketplaces Sector Overview
- FE International, Marketplace App Valuation 2026
- Ad Astra Equity, SaaS Company Valuation & EBITDA Multiples (2026)
- Windsor Drake, 2026 SaaS Valuation Multiples by ARR Band
- Livmo, SaaS Valuation Multiples 2026
- ScaleWithCFO, SaaS Valuation Multiples 2026
- 733Park, SaaS Valuation Multiples 2026 by ARR Band
- SaaS Intelligence, Vertical SaaS Is Buying the Market It Used to Sell Into